

Take-Two Interactive (NASDAQ: TTWO) surged 8.31% to a $224.64 regular-session close on November 10, 2026, as investors positioned for the scheduled November 19 launch of Grand Theft Auto VI. The move came immediately after an unusual earnings combination: weaker year-over-year sales and bookings, but an unchanged full-year outlook and management’s assertion that GTA VI preorders were reaching unprecedented levels. The question is no longer simply whether the game will sell well. It is whether its launch can generate durable earnings and cash flow sufficient to support TTWO’s valuation.
Take-Two’s November 9 fiscal second-quarter earnings release provides the baseline. Fiscal 2027 runs through March 31, 2027, meaning GTA VI is scheduled to launch in the third fiscal quarter, not in the quarter whose results were just reported. Investors must distinguish reported performance from expectations about a release that has not yet occurred.
Why Did Take-Two Stock Jump After Weaker Quarterly Results?
In the three months ended September 30, 2026, net bookings were $1.601 billion, down about 18% from $1.961 billion one year earlier. GAAP net revenue fell to $1.497 billion from $1.774 billion. The company posted a GAAP net loss of $54.0 million, or $0.29 per share, compared with a $133.9 million loss, or $0.73 per share, one year before. These are reported results, not forecasts.
| Measure | Fiscal Q2 2027 | Year-earlier quarter |
|---|---|---|
| Net bookings | $1.601 billion | $1.961 billion |
| GAAP net revenue | $1.497 billion | $1.774 billion |
| GAAP net loss | $54.0 million | $133.9 million |
| GAAP loss per share | $0.29 | $0.73 |
The stock rallied because investors apparently focused on the upcoming release and management’s outlook rather than the backward-looking decline. The company reiterated fiscal 2027 net bookings guidance of $8.0 billion to $8.2 billion. As Reuters reported on November 9, Take-Two also lifted its annual GAAP revenue and profit forecasts while leaving its net bookings target unchanged. The share-price reaction is evidence of more optimistic expectations, not proof that GTA VI has already met sales projections.
What the Price and Volume Charts Reveal
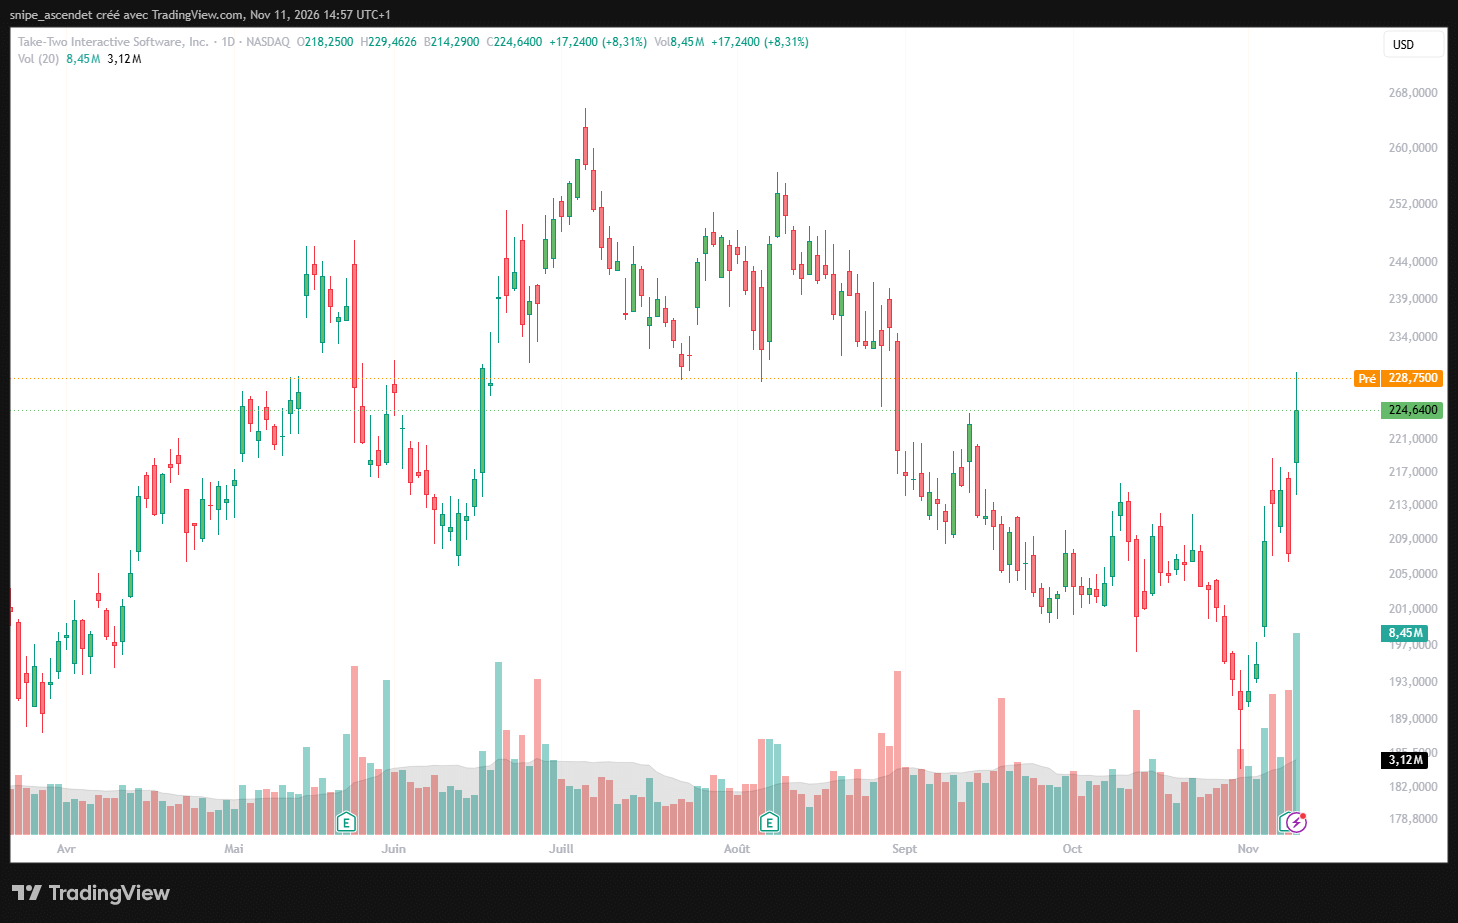
The daily chart shows TTWO closing November 10 at $224.64, up $17.24 or 8.31%. Volume reached approximately 8.45 million shares, versus the displayed 20-session average of 3.12 million. That is about 2.71 times normal recent volume. The higher turnover confirms that the repricing drew substantial activity, although volume alone cannot identify which investors were buying or selling.
The separate four-hour view shows a sharp recovery from a late-October low near $190 and an acceleration after the earnings announcement. On November 11, the screenshot taken at 14:57 Central European Time showed an indicative premarket price around $228.75. Premarket prices can change before the US regular session opens; this is not a confirmed November 11 closing price. A sustained move above the recent $225–$230 trading area would be different from a temporary extended-hours spike.
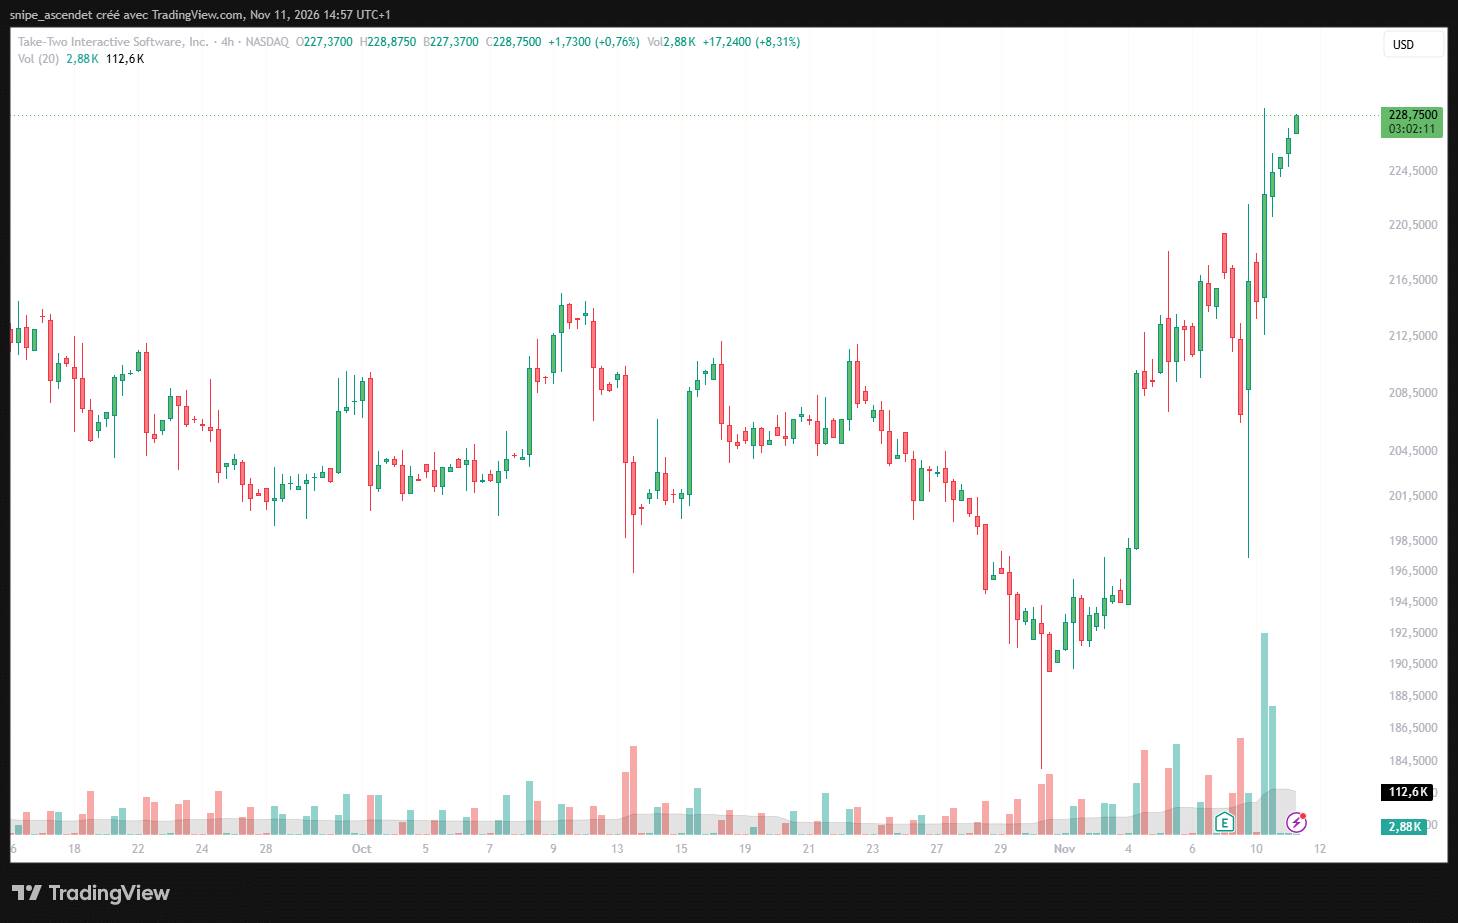
The longer weekly chart adds perspective. TTWO has rebounded strongly, but it remains below the peaks near the $260 area visible in 2025. The current week’s candle is incomplete and should not be treated as a settled weekly return. An earnings-driven rally can reverse when the release generates actual data on unit sales, player activity, and spending.
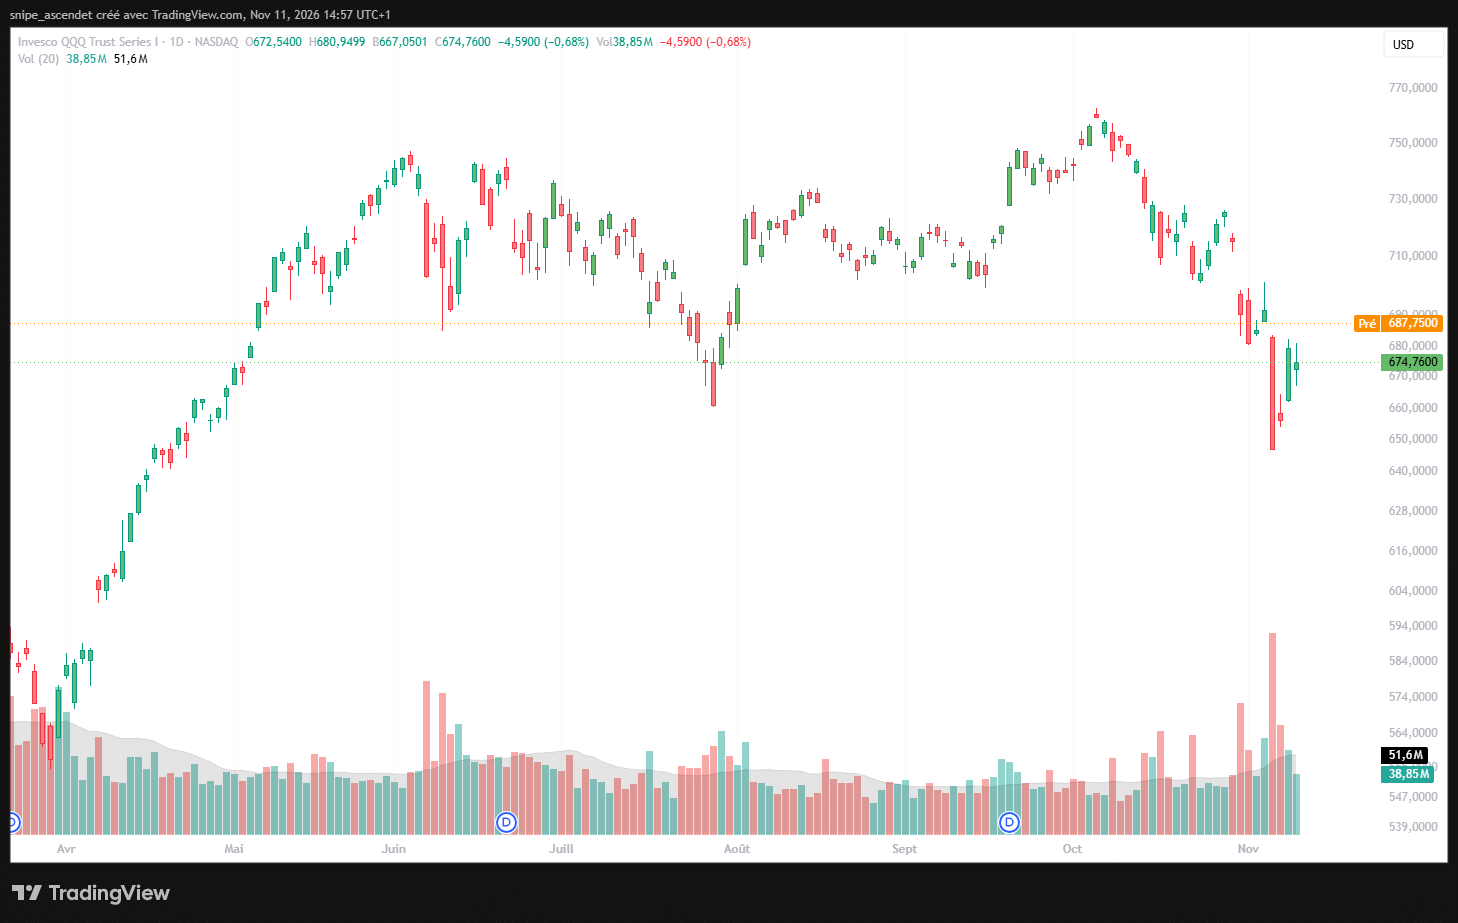
Broader tech stocks were not uniformly rallying. On November 10, the supplied QQQ daily chart shows the Invesco QQQ Trust closing at $674.76, down 0.68%. TTWO’s return exceeded QQQ’s same-day return by 8.99 percentage points, consistent with a company-specific catalyst rather than simply a rising Nasdaq. The comparison does not establish how much of the price move was attributable to preorders, guidance, or short-term positioning.
Net Bookings Are Not the Same as GAAP Revenue
For a game publisher, net bookings measure products and services sold digitally or sold into physical distribution, alongside items such as in-game advertising and licensing. GAAP revenue follows accounting recognition rules. Preorders and cash receipts can precede the period in which revenue is recognized. Treating every preorder as immediately recognized revenue would inflate an earnings estimate.
The distinction matters because Take-Two’s fiscal second-quarter net bookings of $1.601 billion exceeded GAAP revenue of $1.497 billion by approximately $104 million. That difference is not itself incremental profit. For a separate example of why headline growth must be assessed alongside GAAP losses and margins, see DualFinances’ analysis of Hims & Hers earnings.
The company’s recurrent consumer spending contributed $1.302 billion, or approximately 81% of quarterly net bookings, and declined 9% from the comparable year-earlier period. This includes purchases such as virtual currency, additional content, and in-game activity. GTA VI can create a large initial wave of full-game sales, but recurring engagement will help determine how much of its value persists beyond launch month.
How Much of Fiscal 2027 Depends on the GTA VI Launch?
Take-Two expects full-year net bookings of $8.0 billion to $8.2 billion and forecasts $3.35 billion to $3.50 billion in the third fiscal quarter ending December 31, 2026. At the midpoint, the third-quarter outlook of $3.425 billion represents approximately 42.3% of the $8.1 billion annual bookings midpoint. The quarter therefore carries a large part of the financial year’s expected performance, although the company has not isolated GTA VI’s exact contribution within that guidance.
For the full year, management also forecasts GAAP revenue of $7.98 billion to $8.18 billion and GAAP net income of $109 million to $142 million, equivalent to $0.57 to $0.75 in diluted EPS. These are company projections, not reported earnings or guaranteed outcomes. The projections assume timely delivery of planned releases and continued console adoption, among other conditions identified by Take-Two.
Can GTA VI Translate Bookings Into Free Cash Flow?
Revenue growth alone cannot establish investment value. Take-Two’s six-month cash-flow statement through September 30 showed a $173.5 million operating cash outflow and $163.3 million in purchases of fixed assets. Using the simple formula free cash flow = operating cash flow − capital expenditures, the six-month result is negative $336.8 million. These are six-month, fiscal-year-to-date figures and must not be mislabeled as second-quarter cash flow. They also exclude a broader definition of investment beyond fixed-asset purchases.
Management forecasts more than $1.0 billion in operating cash flow for the entire fiscal year and approximately $290 million in capital expenditures. Holding the estimated capital expenditure amount fixed, this would imply more than roughly $710 million of simplified full-year free cash flow. It is an arithmetic implication of management’s forecast, not an achieved result or independently verified cash-flow target. For another company example separating operating cash generation, capital spending, and shareholder returns, see DualFinances’ Lam Research cash-flow analysis.
There is a second important cash consideration. In the first six months, the cash-flow statement recorded $372.4 million of cash usage for software development costs and licenses within operating activities. Thus, the simple free-cash-flow calculation above already reflects that operating cash outflow; adding the same spending again would double count it. Future cash conversion depends on how launch receipts, deferred revenue, marketing, development spending, and ongoing services interact.
A transparent valuation check starts with the disclosed share count. Take-Two reported 187.2 million common shares outstanding as of September 30, 2026. Multiplying that historical count by the November 10 regular-session close of $224.64 produces an illustrative equity market capitalization of $42.05 billion. The exact November 10 share count may differ, so this is an approximation rather than a real-time market-cap quotation.
Dividing $42.05 billion by the midpoint of fiscal 2027 net bookings guidance ($8.1 billion) gives an illustrative price-to-forward-bookings ratio of 5.19 times. Net bookings are not GAAP revenue, so this ratio should not be presented as a conventional price-to-sales multiple. This calculation establishes what investors are paying relative to management’s current annual activity forecast. It says nothing on its own about the stock’s intrinsic value.
Forward GAAP EPS guidance of $0.57 to $0.75 translates into a very high mechanical P/E at $224.64, approximately 300 to 394 times. The denominator is unusually small, so this is a weak standalone valuation test. A better analysis models several years of launch economics, subsequent content spending, development costs, dilution, and eventual free cash flow, then discounts those amounts at a rate consistent with the risk. Related DualFinances analyses explain the contrast between earnings and valuation in Zeta Global’s results and the limitations of forward revenue multiples in Anthropic’s proposed IPO valuation. These are valuation-method examples, not direct business-model peers of Take-Two.
Three Scenarios Investors Can Monitor After November 19
| Scenario | Evidence to monitor | Financial implication |
|---|---|---|
| Upside | Launch meets the scheduled date; strong full-game demand; recurring spending holds up | Greater confidence in FY2027 guidance and longer-term cash generation |
| Base case | Successful release broadly consistent with management forecasts | Bookings increase but valuation depends on sustained margins and cash conversion |
| Downside | Operational issues, lower sell-through, weaker engagement, or heavier spending | Earnings or cash-flow expectations decline despite initial launch revenue |
These are qualitative teaching scenarios, not probability-weighted forecasts or estimated price targets. Investors should also watch the mix of standard and premium editions, refund policies, server performance, player retention, and management’s commentary on future platforms. No official unit-sales result is available before the launch.
Bottom Line: TTWO’s Rally Raises the Execution Bar
Take-Two has a powerful near-term catalyst and an unusually concentrated earnings calendar. Its November 10 stock rally reflects anticipation of GTA VI, not delivery of the financial result. The key checkpoints are a November 19 launch on schedule, actual demand relative to guidance, the conversion of bookings into GAAP revenue, and whether the company’s cash-flow forecast materializes. At approximately 5.19 times guided annual net bookings on an illustrative equity basis, TTWO requires more than a successful opening week to support a durable valuation case.
Investor takeaway: Evaluate the launch as the beginning of a cash-flow test, not as the end of the investment analysis. This article is for educational purposes and does not constitute personalized investment advice. Figures and market prices are dated November 9–11, 2026; premarket values are indicative.